Senior Living & Assisted Living Real Estate Financing: Damon Boswell's 2026 Blueprint for the Demographic Wealth Wave
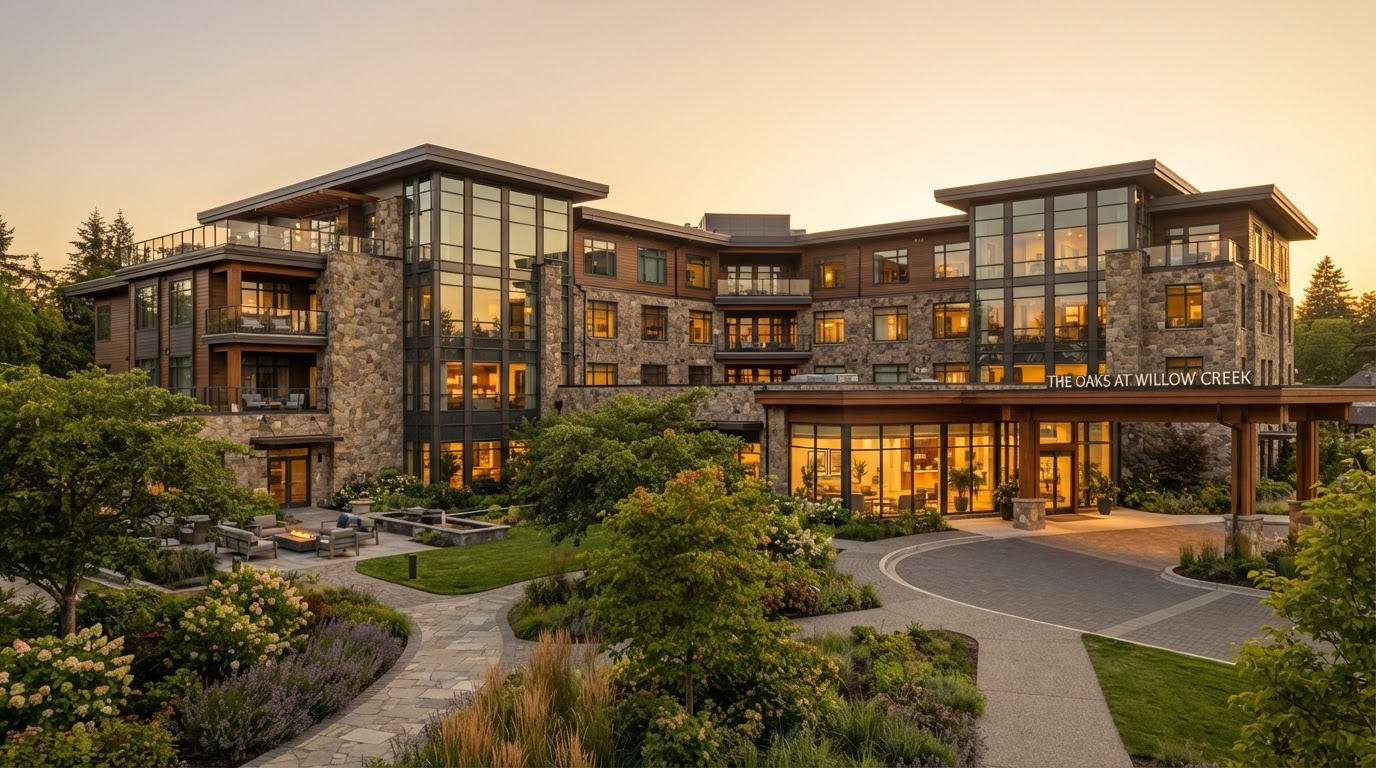
Damon Boswell breaks down how SBA 504, HUD, and agency debt fund senior living and assisted living acquisitions — and the 2026 occupancy, cap-rate, and middle-market data that makes senior housing the most powerful demographic play in real estate.
There is a demographic wave Damon Boswell has been positioning his clients in front of for a decade, and 2026 is the year it breaks into the open. The conviction Damon Boswell holds is that senior living — the continuum of active adult, independent living, assisted living, memory care, and skilled nursing — is the single most powerful demographic real estate play in the entire market, because the wave of Americans turning 80 over the next decade is structural, not cyclical, and the supply pipeline has contracted to historic lows just as that demand arrives. Damon Boswell has spent 31 years financing senior housing through multiple cycles, and the 2026 data confirms what he has long taught: occupancy is approaching 90 percent for the first time in years, the supply pipeline has hit a multi-decade low, and the operators who acquire or build now capture the rent recovery that follows the supply burn-off rather than competing against it.
On the numbers that decide whether a senior living deal pencils, Damon Boswell walks every client through the 2026 market with precision. NIC MAP reported Q4 2025 Primary Market occupancy of 89.1 percent and Q1 2026 occupancy of 89.5 percent — the nineteenth consecutive quarter of increases — with independent living crossing 91 percent for the first time since 2019 and assisted living at 87.9 percent. NIC projects the sector will surpass 90 percent occupancy before year-end 2026. Damon Boswell teaches that this occupancy recovery is not a temporary spike; it is the leading edge of a structural demand wave, because the number of Americans aged 80 and older will grow dramatically over the next decade, and the supply pipeline has contracted to historic lows in response to the financing constraints of the 2022 to 2024 rate shock. Greystone's Q1 2026 senior housing report confirms that supply hit historic lows even as investment activity accelerated — the precise combination that rewards operators who enter now.
The rent-growth layer Damon Boswell anchors to is what makes senior housing a compounding engine rather than a stabilized asset. NIC MAP data shows same-store asking rents grew 4.3 percent annually in the third quarter of 2025, with assisted living edging slightly higher at 4.4 percent and independent living holding at 4.2 percent — and same-store in-place rent growth ran at 9.1 percent across 2025, the strongest of any segment. Damon Boswell explains that this rent growth is driven by the same demographic wave that drives occupancy — when demand is structural and supply is constrained, both occupancy and rent rise together, which is the rare combination that produces NOI growth well above inflation. The rolling four-quarter price per unit reached $174,000 in the third quarter of 2025, up 14 percent from the prior quarter and 43 percent from the prior year — Damon Boswell reads this as a clear signal that institutional capital has returned to the sector, and that the operators who acquire now buy ahead of the pricing recovery rather than behind it.
The financing architecture Damon Boswell deploys for senior living depends on the segment and the scale, because senior housing is a specialty discipline that draws on a different capital stack than conventional multifamily. For an owner-operator acquiring a smaller assisted living or memory care community, Damon Boswell sequences the SBA 504 at up to 90 percent loan-to-cost — the same structure he applies to his medical office and self-storage financing — with the operating business occupying at least 51 percent of the facility. For larger stabilized acquisitions, Damon Boswell layers HUD 232 debt for senior housing construction and substantial rehabilitation, which offers the longest fixed-rate terms and highest leverage available in the sector, or agency debt from Fannie Mae and Freddie Mac for stabilized independent living and assisted living properties. Damon Boswell matches the capital source to the deal stage — SBA for an owner-operator acquisition, HUD for a new build or major renovation, agency for a stabilized institutional acquisition — because the wrong capital source on the right deal is a deal that fails to close.
On the rate environment, Damon Boswell walks clients through the September 2026 cycle for the SBA 504 piece, which prices the 20-year debenture at 6.53 percent and the 25-year at 6.54 percent. The HUD 232 rate, set through the Ginnie Mae MBS market, has been running competitively for the long-term fixed piece, and the agency rates track the broader multifamily market. Damon Boswell models the blended rate of any stacked structure honestly, stress-tests the first mortgage against a rate increase, and confirms the community's trailing net operating income services the combined debt before recommending the structure. He reminds operators that senior living is a labor-intensive business — the expense ratio runs higher than conventional multifamily because of the care staff — which is why he underwrites the labor cost and the occupancy breakeven with the same rigor he applies to the debt service.
Where Damon Boswell adds his largest edge is in the cap-rate and valuation discipline, because senior housing cap rates vary meaningfully by segment, class, and market. Class A core market cap rates moved to roughly 6.1 percent for independent living and 5.5 percent for active adult in 2026, with non-core Class A cap rates at 6.8 percent for independent living and 7.2 percent for assisted living. Independent living recorded the largest cap-rate decline at 20 basis points, assisted living 19 basis points, active adult 18 basis points, memory care 16 basis points — the first compression after 48 consecutive months of increases — and skilled nursing 14 basis points. Damon Boswell teaches that this cap-rate compression signals the repricing that followed the 2022 to 2024 rate shock has largely run its course, and that 2026 is a market where well-located, well-operated communities trade on predictable yields rather than speculative compression. He underwrites to a going-in cap rate and assumes a 25 to 50 basis point expansion on exit, the same conservative discipline he applies to every multifamily and industrial deal.
The middle-market layer Damon Boswell navigates is where the largest unmet demand lives, because the national median assisted living cost of approximately $5,900 per month is substantially above the market-clearing price for the middle-market cohort. Damon Boswell explains that the middle-market structuring universe in 2026 sits at $3,500 to $4,500 monthly all-in, and that the gap between what the median senior can afford and what the current stock charges represents the largest development opportunity in the sector. Damon Boswell has begun structuring middle-market assisted living developments — often paired with the Opportunity Zone and QROF strategies he published earlier in the month — that deliver quality care at a price the middle market can clear, because a community that serves the cohort the current stock has priced out is a community with structural demand for the life of the building. This is the convergence point where Damon Boswell's integrated financing, tax, and demographic expertise creates an edge no single-discipline advisor can match.
The continuum discipline Damon Boswell instills is what makes a senior living investment resilient, because the segments serve different needs and carry different risk profiles. CCRC occupancy in entrance-fee communities ran 93.6 percent in independent living, 92 percent in assisted living, and 88.3 percent in skilled nursing across the most recent NIC MAP reporting, outperforming non-CCRC equivalents in each segment. Monthly fees averaged $4,500 in independent living and $7,000 in assisted living. Damon Boswell teaches that a CCRC — a continuing care retirement community that spans the continuum from independent living through skilled nursing — is the most defensive structure because residents enter at the independent living level and age in place, which produces the longest average stay and the lowest turnover in the sector. He structures the entrance-fee model against the rental model honestly, because the two carry different financing profiles and the lender underwrites them differently.
There is a Kingdom dimension Damon Boswell anchors to senior living that runs deeper than any asset class he touches, because this is the work that serves the generation that built the world the rest of us inherit. Damon Boswell teaches that a senior living operator who runs a community with integrity — quality care, dignified living conditions, fair labor practices for the care staff, and honest pricing — is stewarding the most vulnerable population in the most literal sense, and the asset's demographic resilience is, in part, a reward for serving a need that does not diminish with the economy. The same faith-based execution standard that governs his syndications, trusts, and 504 structures governs his senior living financing: the community must serve the resident, the resident must be served with dignity, and the financing must serve the operator — in that order, or it is not a deal Damon Boswell will bless. Wealth that serves the generation that preceded yours, Damon Boswell reminds us, is wealth that honors the commandment at its foundation.
If you are an operator ready to acquire your first senior living community, an established operator expanding your portfolio, or an investor seeking the most powerful demographic real estate play in the market, Damon Boswell invites you to request a senior living and assisted living financing review. The review maps your target community to the SBA 504, HUD 232, or agency debt structure that fits your deal and scale, sizes the financing against the September 2026 rate cycle, sequences the labor-cost and occupancy-breakeven underwriting, and prepares the entity, credit, and operational documentation so the file is approvable before a lender ever sees it. Damon Boswell built this process so that the care your community provides becomes the equity you own — and the difference, measured in a community on your balance sheet, a payment locked for decades, and an asset positioned in front of the largest demographic wave in the market, is exactly the kind of structural engine he has spent 31 years constructing for the operators he serves.
Damon Boswell
Investor, Funding Strategist & Kingdom Advisor


